Is insurance high on a Miata? A practical checklist for buyers
When you search 'miata for sale', insurance is one of several ownership costs that can shift depending on model year, trim, condition and who will drive the car. This guide explains which listing details most influence premiums and gives clear steps to gather comparable quotes. Use a vehicle history report and pricing insights to reduce uncertainty before you call insurers.
A rav4 used for sale can be a sensible pick for many research-oriented buyers because reliability aggregators rate the model above average and safety ratings are generally strong. This guide explains how to vet listings, what model years tend to be better, and a step-by-step checklist to reduce risk before you buy.
This guide explains how to estimate the cost of buying an R34 Skyline, with attention to import rules, condition-driven price tiers and landed cost. It shows which factors move value, how to verify history and paperwork, and offers a checklist you can follow when you search for a nissan skyline r34 for sale.
This guide helps buyers set realistic expectations for tacoma trucks for sale by explaining the main price drivers and a repeatable method to build conservative, typical, and ambitious offer ranges. It shows how the 2024 redesign, valuation guides, and vehicle history reports interact to change asking prices and reduce purchase risk.
Buying a used Miata is often a balance between driving enjoyment and predictable ownership costs. Insurance is a meaningful part of that balance and it can change depending on the exact car you buy and who will drive it.
This article explains how insurers typically set rates for Mazda MX-5 models, what to look for on a 'miata for sale' listing, and step-by-step actions that help you get accurate, comparable quotes using a vehicle history report and pricing insights.
Insurers price Miata policies mainly on vehicle value, trim, driver profile, crashworthiness and local theft rates.
Order a VIN-based vehicle history report and record exact trim and mileage before requesting quotes to keep comparisons consistent.
Raising deductibles, bundling policies and confirming anti-theft features are common, high-confidence ways to lower premiums with clear trade-offs.
When you search 'miata for sale': why insurance should be part of your checklist
When you search 'miata for sale', the listing gives insurers many of the facts they will use to price a policy. Insurers mainly price policies on vehicle value and repair cost, model year and trim, driver profile, crashworthiness and local theft rates, so what you see on a listing often maps directly to rating inputs Insurance Information Institute.
That means two listings that look similar at first can produce different quotes once you add driver age, location and coverage choices. Market studies show many Miata buyers fall into a moderate premium band for sports cars, but actual quotes depend strongly on personal profile and local market context NerdWallet insurance analysis.
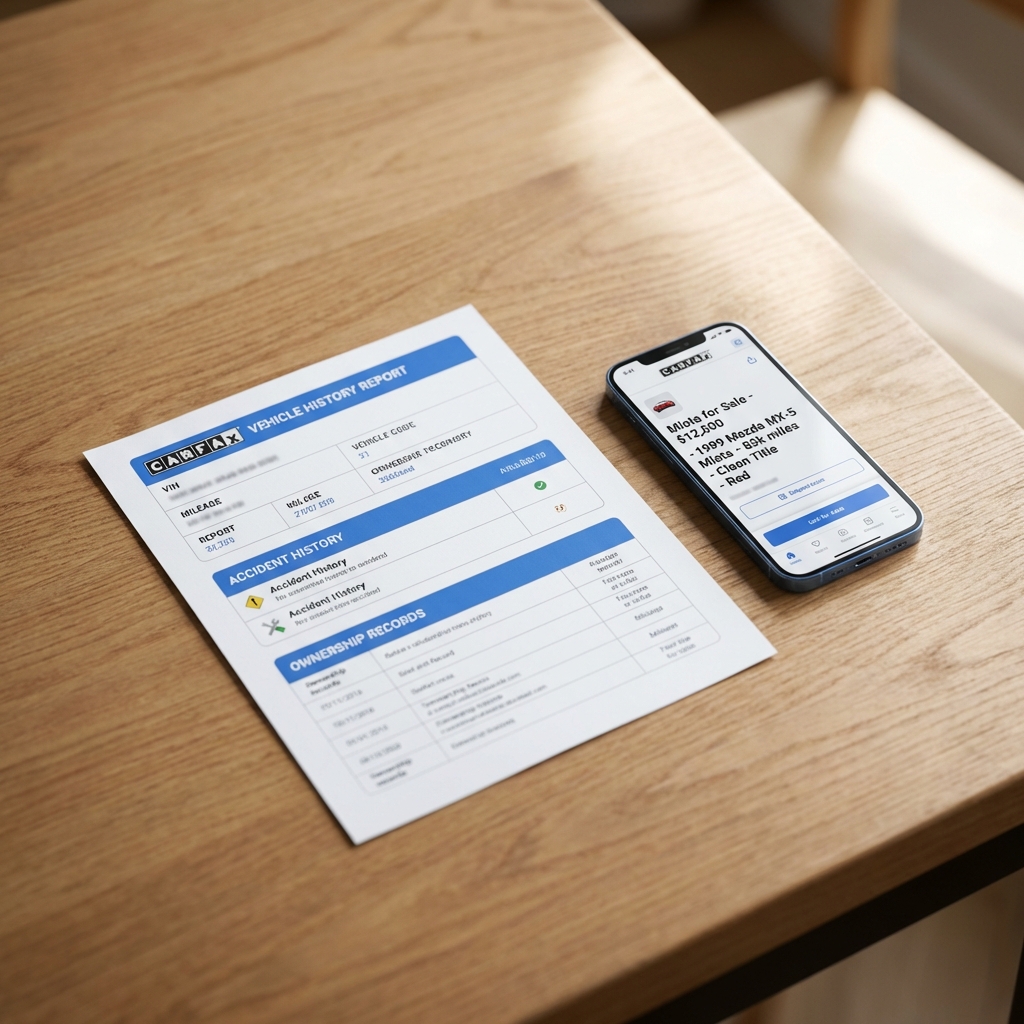
Run a vehicle history report to verify listing facts
Compare listings with verified vehicle history and pricing insights to reduce uncertainty before requesting quotes.
Before you call insurers, confirm the exact model year, trim, mileage and any reported damage on the listing. Use a VIN-based vehicle history report and pricing insights so the facts you give different companies match the listing you intend to buy.
Pay attention to optional equipment, documented accidents, title status and any noted anti-theft devices. Those details often move collision and comprehensive premiums more than the marketing name on the ad.
How insurance interacts with listing details
Listing details like trim, options and documented repairs connect to how insurers estimate replacement cost and repair complexity. A higher trim or rare option typically raises replacement cost and can increase collision-related premiums; insurers reference vehicle value and expected repair costs when setting rates Kelley Blue Book on MX-5 ownership costs.
Driver attributes are separate but critical. The same Miata listed in two different zip codes or owned by drivers of different ages can receive materially different quotes from the same insurer.
Why the same Miata can carry different premiums
Companies weight the core pricing factors differently and state rules also change how some rating elements apply. That explains why a single listing can produce a range of rates when you shop multiple companiesInsurance Information Institute.
To get meaningful comparisons, give each insurer the same exact listing facts and ask them to base quotes on those facts rather than a brief description.
How insurers decide rates: the five factors that matter most
Insurers focus on five broad factors when quoting: vehicle value and repair cost, model year and trim, driver profile and location, crashworthiness and safety equipment, and local theft or crime rates. This framework helps you map listing items to likely rating weightings Insurance Information Institute.
Vehicle value and repair costs affect collision and comprehensive portions of a premium. Expensive parts or limited-availability replacement components tend to push those coverages higher.
Vehicle value and repair costs
High value and high replacement costs increase potential insurer payouts after a loss. That is why exact trim and engine choice on a listing matter: higher trims typically mean higher replacement cost and sometimes more advanced hardware to repair Kelley Blue Book on MX-5 ownership costs.
If a listing shows cosmetic and structural repairs, confirm the details on a VIN-based report before quoting; prior damage and salvage designations materially affect insurer offers.
Driver profile and location
Age, driving record, credit-based scores where permitted and the car's garaging zip code are strong premium drivers. Two buyers quoting the same 'miata for sale' can therefore see different rates because their profiles differ Insurance Information Institute.
Local factors include repair labor rates and how insurers factor regional claim frequency into pricing. That variation is a common source of quoted differences across states and companies.
Safety equipment and crashworthiness
Insurers look for airbags, occupant protection features and available advanced driver assistance systems when they view a vehicle's expected loss severity. Safer designs and recognized safety ratings can help reduce the liability portion of a premium for many buyers IIHS MX-5 ratings.
When a listing shows ADAS or extra airbags, note them for your insurer to check. Confirming equipment on the VIN-based report avoids missed discounts or incorrect rate assumptions.
What to check on a 'miata for sale' listing before you get an insurance quote
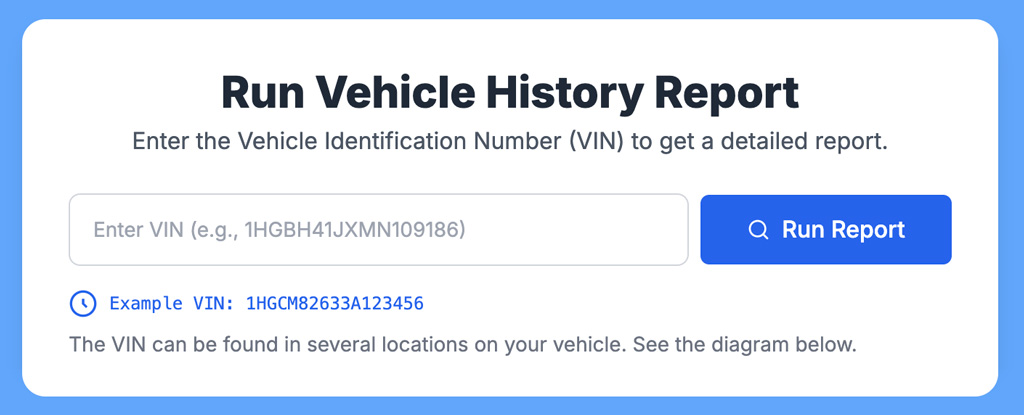
Start with the VIN. A VIN lets you order a vehicle history report that confirms model year, trim code, powertrain, recorded accidents and title status. That verification makes insurer quotes more comparable and reduces surprise re-scores later Kelley Blue Book on MX-5 ownership costs.
Record exact trim, reported options and mileage before you call insurers. Small differences in equipment or engine can change replacement cost assumptions.
Yes. Confirming insurance impact with verified listing facts helps you estimate total cost to own and avoid surprise underwriting decisions after purchase.
Check title status and ownership history on the report. Salvage, rebuilt or inconsistent title records typically lead insurers to ask follow-up questions and sometimes limit available coverages.
Also look for documented service history. A well-documented maintenance record can support value claims, while the absence of service history may prompt closer insurer underwriting.
VIN and vehicle history report
Order a VIN-based vehicle history report early. The report confirms whether the listing's trim and equipment match factory specs, and it shows reported damage or title problems that matter for coverage and pricing.
Providing that same report summary to each insurer helps keep quotes apples-to-apples and reduces back-and-forth on underwriting questions. Share the VIN-based report or use a VIN decoder tool like the one on the site VIN decoder so insurers see the same equipment listing.
Exact trim, optional equipment and powertrain
Trim and powertrain choices change replacement parts and labor expectations. Confirming the exact trim from the VIN can clarify collision exposure before you accept a quote, especially for high-trim examples that include pricier components.
Note any anti-theft hardware, factory immobilizers or tracking hardware on the listing. Insurers may offer lower comprehensive premiums when those features are present.
Title status, ownership history and service history
Title issues, previous owners and service gaps are underwriting flags. A salvage or rebuilt title typically narrows insurer options and raises costs for some coverage types.
Capture screenshots or copy key listing fields into a notes app so every insurer you call has the same facts to price against.
Crashworthiness and safety ratings: what IIHS and NHTSA say about the MX-5/Miata
Recent IIHS and NHTSA assessments for tested MX-5/Miata model years generally show favorable crashworthiness, which tends to reduce liability-related insurance pressure for many buyers IIHS MX-5 ratings.
NHTSA crash test summaries provide another insurer-facing data point; insurers often use both organizations' results when estimating expected injury severity for a model NHTSA 2023 MX-5 information.
IIHS test results for relevant model years
IIHS notes specific strengths and limitations for tested model years. When a listing indicates tested equipment levels and model year, mention those details to insurers so they align rating inputs with the correct test data.
Remember that available ADAS and the exact tested trim matter. A favorable IIHS result for one trim does not automatically apply to a different configuration.
NHTSA crash ratings and what they mean for premiums
NHTSA star ratings summarize crash performance across tested areas. Insurers interpret these ratings in light of other loss data to estimate injury severity and liability exposure.
When the listing includes specific safety gear, confirm it via the VIN report so insurers can accurately apply any equipment-related rating adjustments.
Theft risk and anti-theft: what affects comprehensive and collision for a Miata
The National Insurance Crime Bureau summaries show Miatas are not typically among the highest-theft sports cars, which can reduce comprehensive exposure compared with higher-risk models NICB theft summaries.
That said, theft risk is local. Insurers price comprehensive and collision partly on local crime rates, so a low national theft profile does not guarantee low premiums in a higher-theft zip code.
Verify anti-theft features listed on the ad or report. Factory immobilizers, alarm systems and vehicle tracking are the kinds of equipment insurers may recognize when calculating comprehensive discounts.
When the listing lacks clear anti-theft information, note that and ask the seller to confirm before you finalize a purchase or get final insurance terms.
NICB theft summaries and Miata theft status
NICB data provides model-level theft context that insurers use alongside local crime statistics. For Miata buyers this broader context often places the MX-5 below the highest-theft sports cars, but local patterns still drive insurer pricing in many areas NICB theft summaries.
Because theft exposure is layered, check both national model trends and local police reports or insurer notes for a complete view.
Anti-theft features that insurers may reward
Insurers commonly offer discounts for factory immobilizers, steering locks, alarms and OEM tracking systems. Confirm and record any such features on the listing so insurers can apply available savings.
If the vehicle has an after-market tracker, ask the insurer whether it accepts that device for a discount; some do and some do not.
Trim, powertrain and repair costs: why similar Miatas can insure differently
Higher trims and rare options raise vehicle value and replacement costs. Insurers charge more when expected repair bills or replacement parts are costly, so trim matters beyond marketing labels Kelley Blue Book on MX-5 ownership costs.
Confirming exact powertrain and options via the VIN reduces guesswork and helps insurers avoid conservative re-pricing because of uncertainty.
How higher trims and optional equipment affect replacement costs
Leather, upgraded audio, adaptive components and other costly extras can increase repair expenses. That tends to move collision premiums higher than for base models with simple components.
When you see atypical equipment on a listing, capture it for insurers so the quote reflects the car you plan to buy and not a generic MX-5 configuration.
Parts and labor considerations for common Miata repairs
Some parts are shared across years and trims; others are trim-specific. Insurers and repair shops factor parts availability and dealer-only items into estimated repair time and cost, which then informs premiums.
Asking the seller about recent parts replacement or known service issues can also clarify likely near-term maintenance costs that insurers consider when modeling exposure.
Typical premium ranges and why two quotes can differ for the same 'miata for sale'
Analyst and insurer summaries from recent years place many Miata buyers in a moderate annual premium band for sports cars, often in the mid-three-hundreds to low-four-thousands for a wide set of drivers and coverage choices, though exact figures vary by profile and location NerdWallet insurance analysis.
Two common reasons identical listings return different quotes are state rating rules and how each insurer weighs driver attributes like age and driving history. That is why consistent listing facts and multiple insurer checks are essential Insurance Information Institute.
estimate local premium variance from a base rate
quick local estimate only
Use a simple comparison checklist or a local calculator to see how age and coverage choices change likely premiums. Small changes in driver factors often move quotes far more than small differences in listing price.
Gather at least three insurer quotes using the same recorded listing facts to compare effectively. Ask each insurer to confirm the same trim, VIN-based equipment, and declared mileage in their written quote.
Market studies and insurer rate summaries
Rate studies synthesize many individual quotes and help set expectations, but they cannot replace a quote based on your exact profile and the listing's verified facts.
Use price analysis labels and local market context to see whether a listing price plus expected insurance looks reasonable for your area.
Common sources of regional and age-based variation
Regional differences include state insurance rules, local claim frequency, and repair cost levels. Age-based variation reflects observed claim rates by age group and licensing status, which insurers translate into price adjustments.
These factors are why two otherwise identical Miatas can cost different amounts to insure for different buyers in adjacent zip codes.
Practical steps that commonly reduce Miata insurance costs
High-confidence actions that often reduce premiums include increasing deductibles on collision and comprehensive, bundling auto and homeowner or renter policies, maintaining a clean driving record, and shopping multiple insurers Insurance Information Institute.
Each action has trade-offs. Raising your deductible lowers the premium but increases out-of-pocket cost if you file a claim. Bundling can provide discounts, but compare underlying policy coverage levels carefully.
Coverage choices and deductible strategies
Consider whether full collision is necessary for an older, high-mileage Miata; for newer or financed cars collision is often required. If you choose higher deductibles, keep the payable amount in mind for realistic out-of-pocket planning.
When you request quotes, get premium numbers for at least two deductible levels to see the trade-off in real terms.
Behavioral factors and discounts to ask about
Ask insurers about safe-driver discounts, multi-policy discounts, low-mileage discounts and any specific savings for factory anti-theft systems. Confirm that the insurer accepts the equipment shown on your VIN report.
Keeping a clean record and documenting maintenance can help preserve discounts over time and reduce long-term ownership cost.
Modifications, track use and high mileage: underwriting flags to watch
Performance modifications and declared track use commonly cause insurers to raise premiums or require special coverage. Insurers consider modifications a change in expected risk and may exclude track-related incidents unless you buy a specific endorsement Insurance Information Institute.
High mileage increases exposure because more miles mean higher chance of a claim; older, high-mileage examples can move toward higher collision or liability rates depending on condition and driver profile.
How performance mods and non street use influence quotes
After-market performance parts or altered suspension and engine work are underwriting flags. Disclose known modifications when requesting quotes to avoid claim denials later.
If you plan track days, ask insurers whether your policy covers that use and what endorsements or special policies are needed.
Why high mileage changes exposure
Insurers see higher mileage as higher risk because the probability of a loss grows with miles driven. Documented high mileage in a listing should influence your choice of coverage and deductible levels.
For high-mileage cars, focus on keeping good maintenance records and check whether collision coverage remains cost effective relative to potential out-of-pocket repair expenses.
Quick checklist: what to gather from the listing before you call insurers
Essential facts to record: VIN, exact model year and trim, current mileage, title status and any documented accidents or service records. These items let insurers price against the same facts and reduce inconsistent quotes Kelley Blue Book on MX-5 ownership costs.
Documents and reports to have ready: a recent VIN-based vehicle history report, photos of visible damage or modifications, and any service history notes the seller provides.
Essential facts to record
Copy the VIN and take a screenshot of the listing. Note option packages and any factory packages listed, since these affect replacement cost and available safety equipment credits.
Record title notes exactly as shown and ask the seller to clarify any discrepancies before quotes are finalized.
Documents and reports to have ready
Order a vehicle history report before you call insurers. Use it to confirm mileage, title events and any reported collisions so all your quotes use the same baseline facts.
Having the report ready also helps you ask targeted insurer questions about accepted discounts for safety or anti-theft features.
Three buyer scenarios: how insurance outcomes tend to differ
Scenario one, a young driver buying a newer high-trim Miata, tends to face relatively higher premiums driven by age and the higher replacement cost of the vehicle. The listing will show features and trim that increase replacement cost and insurer exposure Insurance Information Institute.
Scenario two, a middle-aged commuter with a clean record, usually has more moderate premiums if the listing indicates a standard trim and documented maintenance. Driver history and stable garaging often lower insurer adjustments insurer summariesNerdWallet insurance analysis.
Scenario three, a high-mileage older-owner example, typically shows lower replacement cost but higher exposure from miles driven; that trade-off changes how collision and liability components are priced.
Young driver, newer high-trim Miata
High trim plus a younger driver usually raises cost because both replacement cost and experience-based risk increase insurer expected loss. Confirming factory equipment and asking about discounts is especially important in this scenario.
Consider a higher deductible and broader insurer shopping to narrow price differences among companies.
Middle-aged commuter with clean record
A buyer with stable driving history often gets more favorable rate treatment. For this profile the listing's documented service history and confirmed safety features matter more for marginal savings.
Bundling policies and confirming anti-theft equipment can lead to meaningful discounts for this buyer type.
High-mileage older-owner example
High miles often shift the balance between keeping collision and accepting higher out-of-pocket risk. For older Miatas that are well maintained, some buyers opt to drop collision and carry liability plus comprehensive depending on condition.
Use the vehicle history report to document maintenance and avoid insurer re-pricing based on missing service records.
Common mistakes buyers make when estimating Miata insurance
Assuming all Miatas carry the same premium is common. Small differences in trim, model year, modifications or location can change quotes significantly, so treat averages with caution Insurance Information Institute.
Forgetting to report modifications or track use to an insurer can lead to denied claims or higher rates when discovered. Always disclose known changes when you request quotes.
Assuming all Miatas carry the same premium
Treating a model name as sufficient information is a frequent error. Capture the VIN and confirm trim and equipment before relying on general averages.
Use pricing insights to compare a listing's price and its likely insurance impact in your local market.
Forgetting to report modifications or track use
Failing to disclose modifications can void coverages or cause surprise underwriting changes. Be transparent with insurers and verify acceptable coverage for non street activities.
If you plan modifications after purchase, discuss them with your insurer first to understand their effects on coverage and cost.
Relying on vague averages without VIN confirmation
Vague averages help set expectations but do not substitute for a quote based on verified listing facts. Order a VIN-based report and get multiple insurer quotes to see actual pricing for your profile.
Consistent facts across quotes make comparisons meaningful and reduce the chance you overlooked a listing detail that affects price.
Next steps: how to combine listing research and insurance quotes before you visit a dealer
Step three, gather at least three insurer quotes using the same recorded facts and ask each insurer about discounts and how they treat modifications or track use. This approach helps you compare total cost to own more accurately Insurance Information Institute.
Keep CarFax Deals mentions light and factual: use the vehicle history report and pricing insights it provides to reduce uncertainty and surface risk signals before you get quotes.
When you have written quotes, compare coverage levels and out-of-pocket exposure, not just the premium number. That will help you make a clearer decision when you visit the dealer.
Insurance can vary substantially because insurers weigh driver profile, state rules and local claim patterns differently; using identical listing facts with multiple insurers gives the most comparable results.
A vehicle history report that confirms no reported damage and clear title helps insurers avoid conservative re-pricing and can improve quote accuracy, though any premium change depends on other factors like driver profile.
Not always, but performance or safety-related modifications commonly raise underwriting scrutiny and can increase premiums unless you confirm acceptable coverage and disclose changes to insurers.
Use the checklist in this article to gather consistent facts from any 'miata for sale' listing before you call insurers. Confirm trim, VIN, title status and any reported damage to reduce surprises in underwriting.
Collect at least three written quotes using the same recorded listing facts and compare coverage details, not just premium numbers, to make a clearer ownership decision.
 Blog